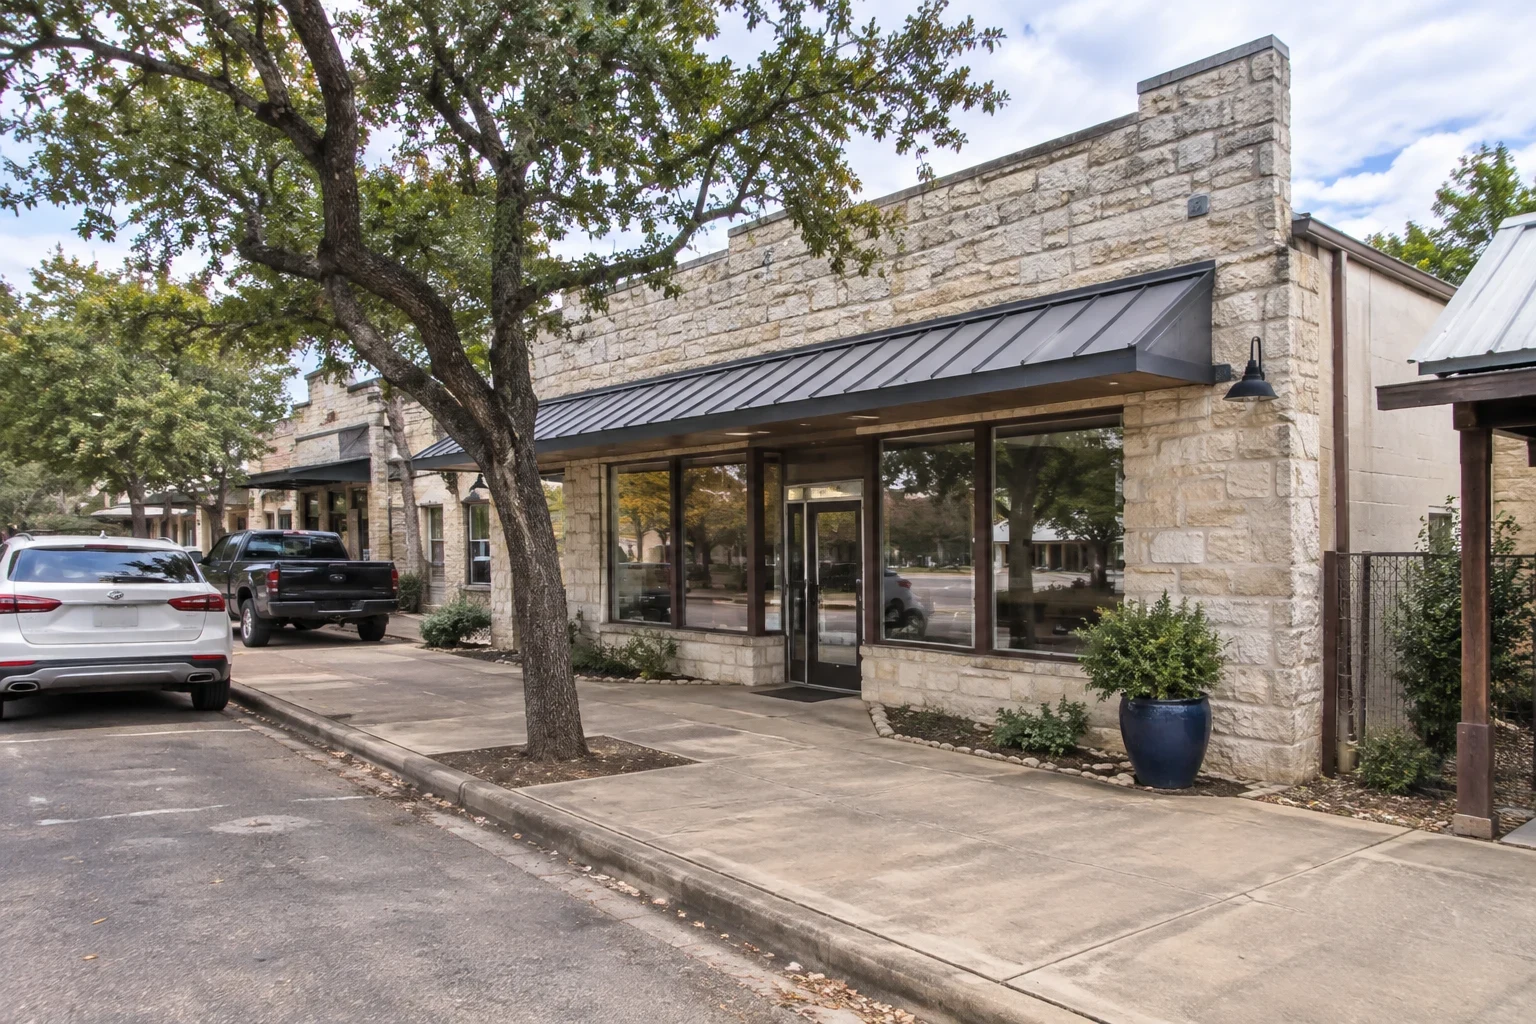
Wimberley Home Loans, Plus the Nearby Towns We Serve
Buyers, refinancers and investors in Wimberley and the communities close by work with us for one reason: plain answers. You learn what you qualify for, what moves your rate and which loan suits the property. Meet us at our office or talk by phone or video.
Who we work with, and where
Many of the borrowers we talk with live in or are shopping for property in Wimberley, San Marcos, Kyle and Buda. Others are buying in Dripping Springs, Belterra, Redwood and Canyon Lake. Because most of our work runs by phone and video, a longer drive is rarely a problem. Questions get answered and most paperwork gets signed without a trip across the county.
The loan options do not change with the town. Purchase buyers usually start with conventional, FHA, VA or USDA financing. Owners who want to borrow against equity often look at a HELOC, self-employed buyers may fit a bank statement loan, and investors or anyone buying before selling tend to ask about hard money and bridge loans. What does vary is the property, and that can steer you toward one loan over another. The points below are the local ones we see most often in a file.
Towns we cover from Wimberley
- Wimberley
- San Marcos
- Kyle
- Canyon Lake
- Buda
- Dripping Springs
- Belterra
- Redwood
Not on the list? Call (512) 782-8931 and ask.
What affects a loan around here
Rural property and USDA eligibility
Some addresses outside the bigger towns may fall in USDA-eligible areas, which can mean no down payment for buyers who meet the income limits. Eligibility goes by the exact address, so we check it before you get your hopes up or rule it out.
Wells, septic and acreage
Properties on land often have a private well or septic system. Many loan programs ask for water tests or septic inspections, and appraisals on acreage can take longer because comparable sales are harder to find. We tell you early which reports your loan will need so closing does not get pushed.
Flood zones near creeks and rivers
A property close to water may sit in a mapped flood zone. If it does, the lender will require flood insurance, and that premium becomes part of your monthly payment. We check the flood status early so the number you plan around is the real one.
Property taxes and HOA dues
Texas has no state income tax, but property taxes are relatively high and they go into your escrow payment. Newer master-planned neighborhoods usually add HOA dues too. Both count toward your debt-to-income ratio, so we include them when we tell you what you qualify for.
Texas rules on cash-out and equity
Texas limits how much equity you can borrow against a primary residence, generally to 80 percent of its value across all loans. That rule shapes every cash-out refinance and HELOC we write here, and we walk through the math with you before you apply.
Buying or refinancing nearby?
Let us know the town, your price range and how much you have set aside. You will get a rate quote and a plain opinion on which loan suits the property. When the timing feels right, pre-qualification can begin during that same conversation.